The best time for Denton County buyers to shop for home insurance is the day your offer is accepted, so you have quotes in hand before your option period ends. That way, if a quote comes back much higher than you planned, or a company won't write the policy, you can still negotiate or walk away and keep your earnest money. Waiting until the week of closing leaves you with fewer choices and no easy exit.
Here is why timing matters so much in Texas right now, what drives the price of a policy, and how to protect yourself while you are under contract.
Why buyers should shop for home insurance during the option period
Under the standard Texas resale contract, TREC No. 20-19, paragraph 5B gives you "the unrestricted right to terminate" during the option period you negotiate. Notice has to be delivered by 5:00 p.m. local time on the last day. Once that window closes, a surprise insurance bill is usually your problem, not a way out.
The contract itself points you to an insurance agent. Paragraph 10A tells buyers to consult one before change of ownership, and paragraph 12A(2) lists hazard and flood insurance premiums and insurance reserve deposits as buyer expenses. Your lender will also want proof of coverage before it funds the loan, and the premium usually becomes part of your monthly escrow payment.
So we suggest a simple order of operations:
- Before you write an offer: ask an insurance agent or two for a ballpark on homes like the ones you're touring.
- Day 1 of the option period: send the address to two or three insurance agents and ask the seller for the home's claim history.
- During inspections: forward the roof findings and the roof's age to your agents. They can change the quote.
- Before the option period ends: pick a policy, or use what you learned to negotiate.
If you are using a mortgage, there is a second, narrower protection. Paragraph 2B of the Third Party Financing Addendum (TREC No. 40-11) lets you terminate and get your earnest money back if your lender determines the property does not satisfy its underwriting requirements, including insurability. You have to give notice on or before the 3rd day before the closing date, with a written statement from your lender. That helps when a home can't be insured to your lender's standards. It does not help when a policy is simply more expensive than you hoped, which is why the option period is still your best window.
We walk through how the option period and option fee work in our guide, What Is the Option Period in Texas?
Buying in Denton County this winter? Schedule a free buyer consultation and we'll talk through your budget, including insurance and taxes, your timing and how to plan your option period.
What drives Texas home insurance prices
Texas premiums climbed fast in recent years. According to the governor's office, as reported by FOX 7 Austin on September 18, 2026, the average Texas premium rose from under $2,000 in 2020 to over $3,500 in 2026. The Texas A&M Real Estate Research Center found that DFW homeowners paid an average of $238 a month for insurance in 2024 (Covered But Costly, July 2026).
The good news: the Texas Department of Insurance reported on October 8, 2026 that most companies filing homeowners rate changes since July 1 proposed decreases, averaging 4.3% over the prior 90 days. TDI also notes that nearly 160 companies sell home and auto insurance in Texas, so shopping around pays.
For any one house, these are the big factors:
- The roof. Its age, material and condition matter more than almost anything else. Hail is a major reason: Texas led the country in major hail damage events for the 11th straight year, with 902 in 2025 (KVUE via NICB, May 2026).
- Claim history. Past claims on the home, and on you, can raise the price.
- Distance to fire protection. TDI suggests asking how far the home is from the fire department and whether it is paid or volunteer (TDI buyer questions).
- Your deductible. Many Texas policies now use a percentage deductible for wind and hail, often 2%, rather than a flat dollar amount.
- Safety features. Alarm systems, sprinklers and a newer roof can qualify for discounts, according to TDI.
Hypothetical example: how a percentage deductible adds up
A percentage deductible is figured on your dwelling coverage, not the size of the claim. This is a made-up example, not a quote:
| Hypothetical line | Amount | Where it comes from |
|---|---|---|
| Dwelling coverage (hypothetical) | $400,000 | Assumed for illustration only |
| Wind/hail deductible | 2% | Common Texas level, per United Policyholders as cited by KVUE/NICB |
| You pay before coverage starts | $8,000 | Calculation: 2% x $400,000 |
Before you choose, make sure that number would fit in your savings after closing.
Ask for the home's claim history (CLUE report)
A CLUE report shows claims filed on a property over the past seven years, even under earlier owners. TDI says buyers can ask the owner to show them one, and owners can get a free copy each year from LexisNexis (TDI: Check your property's insurance claim history). A past roof or water claim isn't a deal breaker, but you'll want to know whether the repair was done and how it affects your quote.
Flood insurance is separate, and timing matters
Most home insurance does not cover flooding. Under the National Flood Insurance Program, a new policy usually has a 30-day waiting period, but there is no waiting period when the policy is bought in connection with making a mortgage loan. A seller can also transfer an existing NFIP policy to the buyer (FEMA NFIP real estate Q&A, August 2025). If the home sits in a high-risk flood zone and you have a government-backed loan, your lender will require flood coverage. You can look up any address at FEMA's Flood Map Service Center.
What this looks like in Corinth and Oakmont
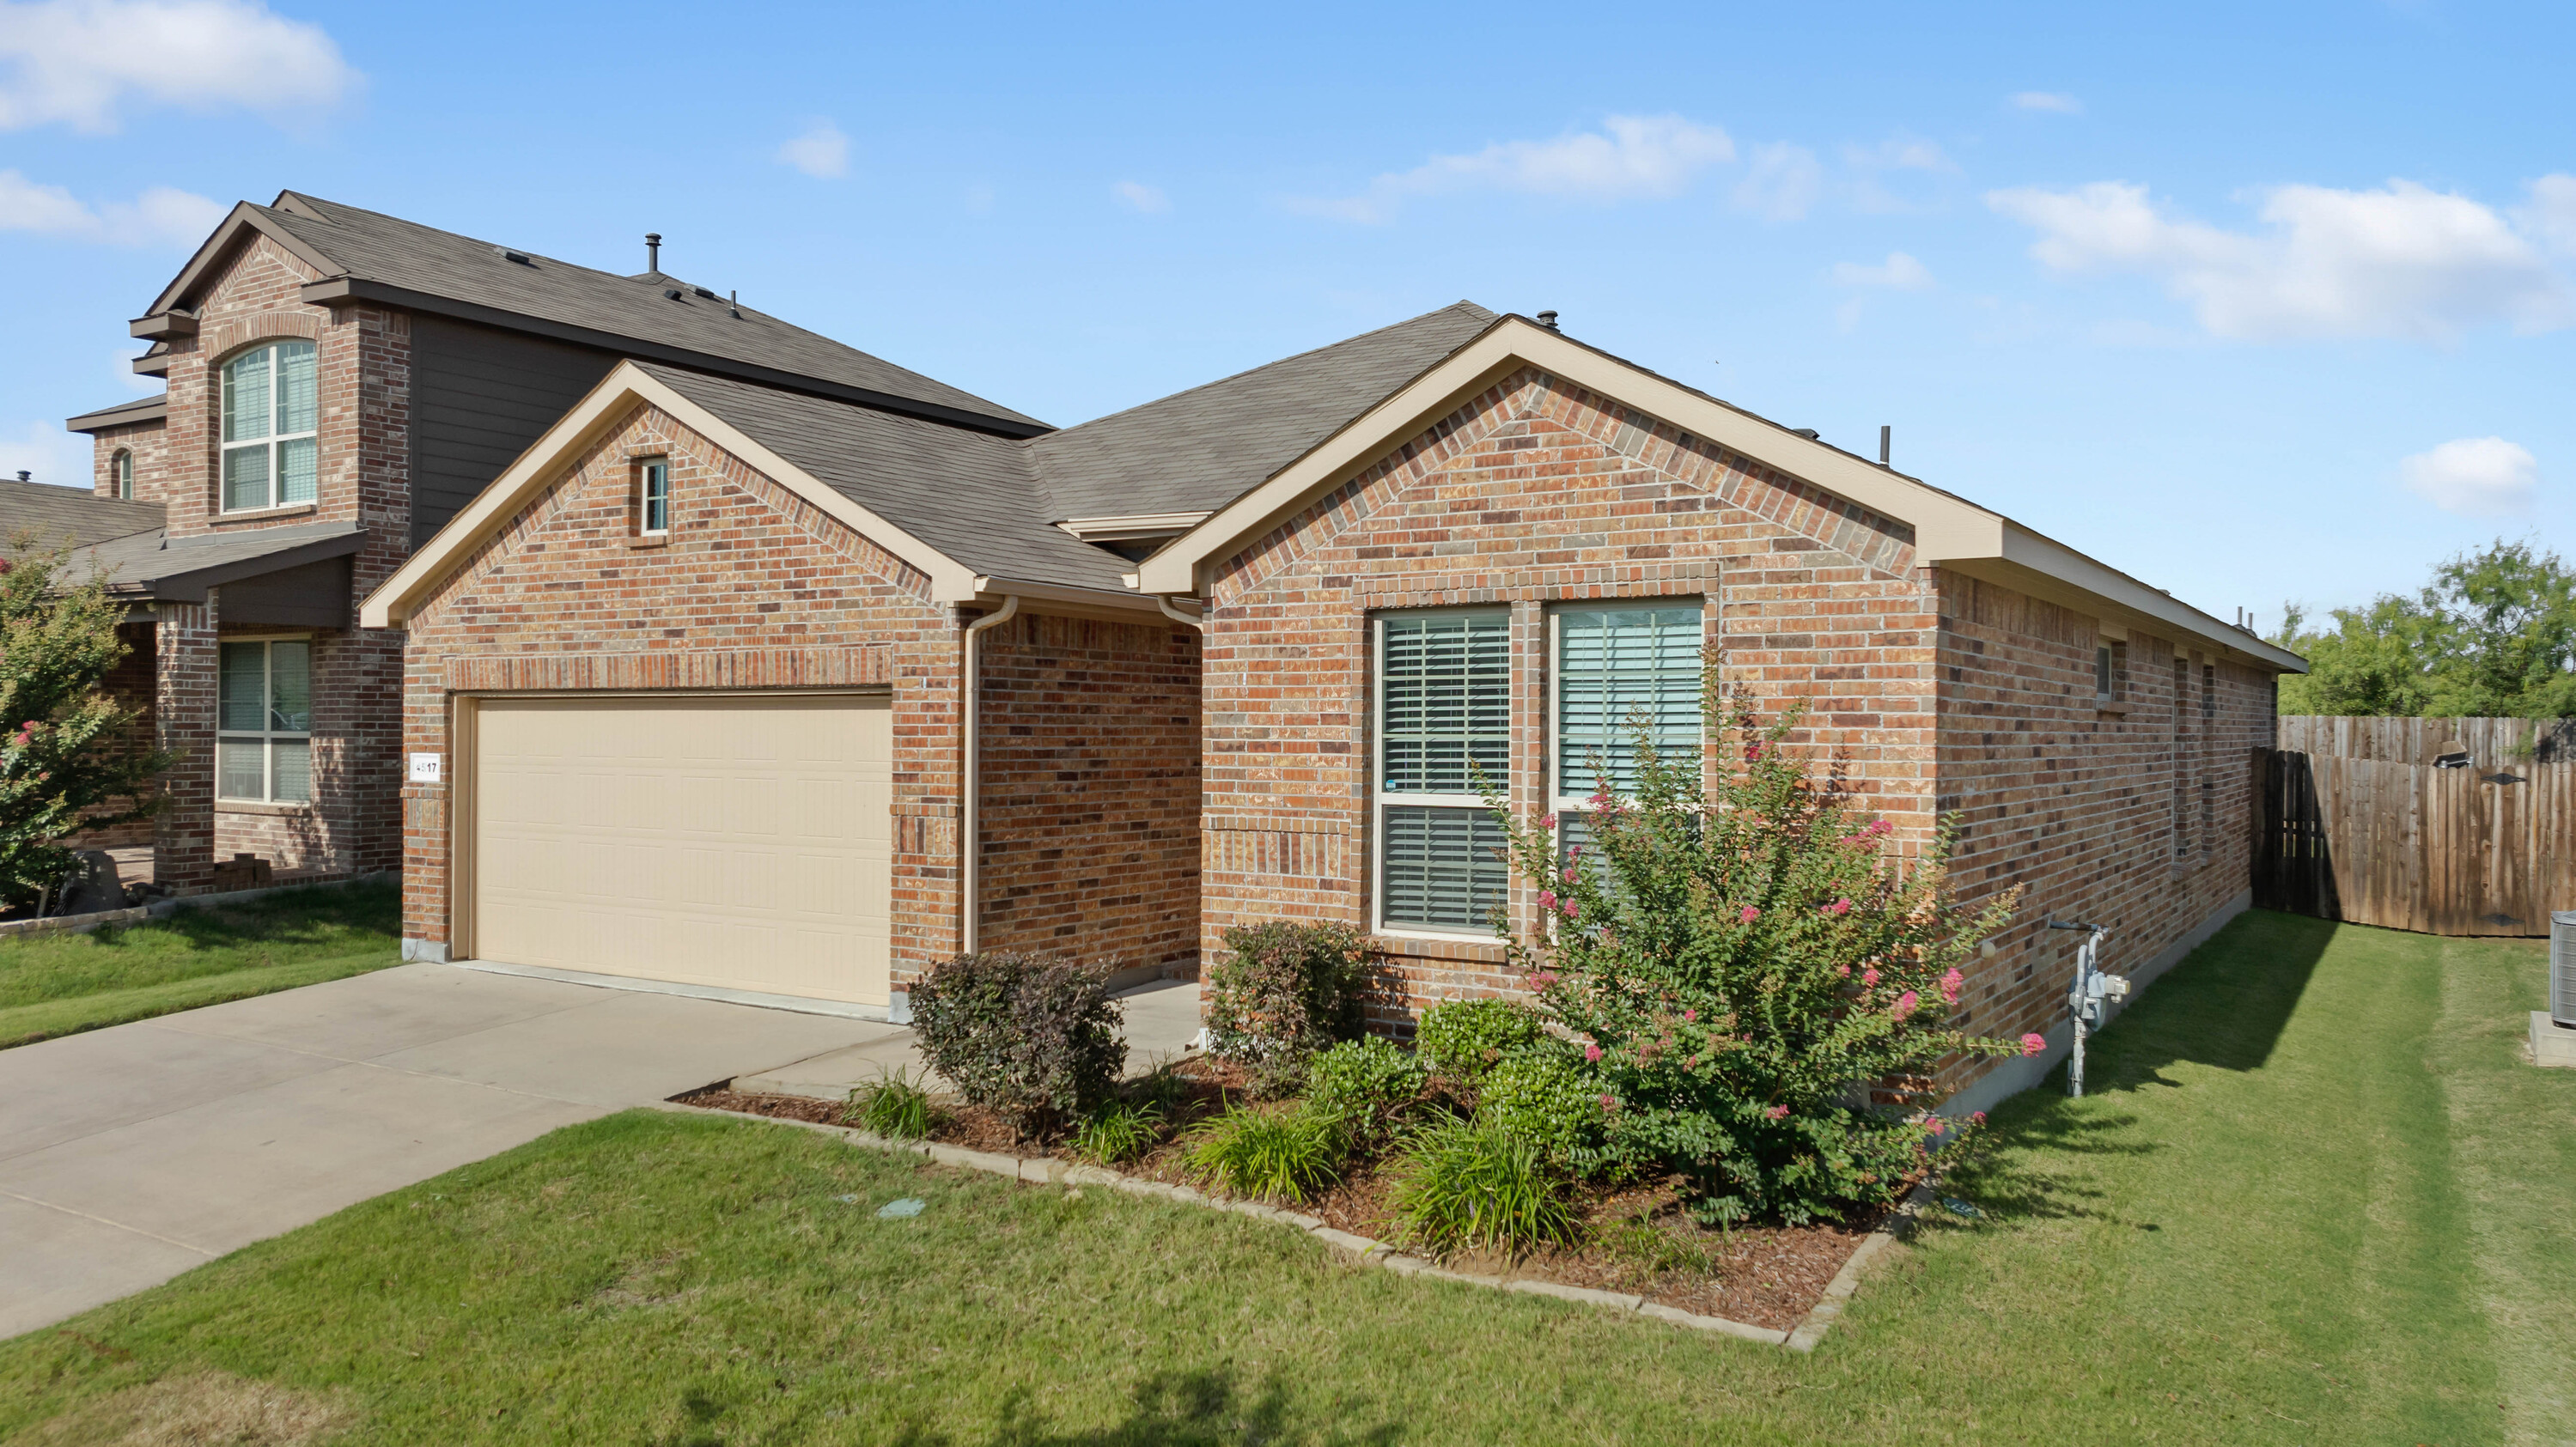
A good share of the resale homes for sale in Corinth were built in the 1980s, 1990s and early 2000s, based on our site's MLS search in November 2026. It is not unusual for homes that age to have had a roof replaced after hail. For homes in Oakmont Country Club Estates and nearby neighborhoods, we ask sellers early for the roof's install date, the material and any receipts. If a home has an impact-resistant roof, tell your insurance agent. TDI issued a bulletin in September 2026 (reported by FOX 7 Austin) urging companies to offer discounts for impact-resistant and FORTIFIED roofs, though it set no required amount.
Ready to look? Search Corinth homes for sale, then plan your insurance shopping alongside the rest of your buyer closing costs in Denton County.
Frequently asked questions
When should I get homeowners insurance quotes when buying a home in Texas?
Start the day your offer is accepted and have quotes before your option period ends. That gives you time to compare and still use your right to terminate if the cost doesn't work.
Can I back out if the insurance quote is too high?
During the option period, yes. TREC No. 20-19 paragraph 5B gives buyers an unrestricted right to terminate by 5:00 p.m. on the last day. After that, paragraph 2B of the Third Party Financing Addendum (TREC No. 40-11) only helps if your lender determines the home does not meet its requirements, including insurability, not if the policy is just expensive.
Does homeowners insurance cover flooding?
Usually not. Flood coverage is a separate policy. NFIP policies usually have a 30-day wait, but not when bought in connection with a new mortgage loan.
What is a CLUE report and how do I get one?
It lists insurance claims on a property for the past seven years. TDI suggests asking the seller for it; owners can request a copy from LexisNexis.
Let's plan your purchase together
Insurance is one piece of what a home really costs each month. Schedule a free buyer consultation and we'll talk through your budget, your timing and your options, then line up the questions to ask before your option period ends.
Have a question you want us to answer? Send it to us.
This post explains how things generally work and isn't insurance, legal or lending advice. For your own coverage, talk with a licensed insurance agent and your lender.
Photo credits: Photos from the Airheart Realty Team.
Get our newest answers in your inbox. Every Wednesday, The Heartbeat brings you our latest blog posts, plus North Texas market numbers, a home tip and local events. Subscribe free.